Cumulative Delta Explained for Futures Traders
Understand what CVD measures, why it can disagree with price, and when that disagreement is worth investigating.
Updated October 16, 2026 · 11 min read
Educational content with links to Sato's paid VIP and mentorship offers. Examples are hypothetical unless labelled otherwise. Futures trading involves substantial risk of loss; delta and divergence do not guarantee results.
Cumulative delta is the running total of buying aggression minus selling aggression from a selected starting point. With bid/ask trade data, it adds ask-executed volume and subtracts bid-executed volume. Compare that effort with price movement at a prepared level—not with the assumption that a rising line means buy.
Cumulative delta is useful because it separates two questions traders often confuse: who is trading aggressively? and is that aggression moving price? A strong buying print with no upward progress can tell a different story from the same print during a clean breakout. This guide explains the calculation, the data limitations and a practical way to read that difference on ES and NQ.
What cumulative delta actually measures
Every futures transaction has both a buyer and a seller. Delta does not reveal a surplus of buyers, the number of accounts entering, or whether an institution is opening a position. It classifies the initiating side of traded volume.
In the usual bid/ask model, an aggressive buyer executes against a resting offer; an aggressive seller executes against a resting bid. Ask volume contributes positive delta and bid volume contributes negative delta. The passive counterparty still exists, but its willingness to absorb the transaction is not represented as a separate opposing market order.
That distinction explains why “buyers are in control” is often too strong a conclusion. Buyers may be initiating more trades while passive sellers successfully prevent an advance. CVD measures classified effort. Price reveals the outcome of that effort in the surrounding liquidity.
For the broader relationship between aggression, liquidity and execution, start with orderflow trading explained. CVD is one part of that framework, not a replacement for it.
Cumulative volume delta calculation: a worked example
The basic calculation is bar delta = ask volume − bid volume. Then current CVD = previous CVD + current bar delta. Here is a deliberately simplified three-bar example starting at zero; these are invented teaching numbers, not a trade record.
| Bar | Ask volume | Bid volume | Bar delta | CVD |
|---|---|---|---|---|
| 1 | 800 | 500 | +300 | +300 |
| 2 | 350 | 650 | −300 | 0 |
| 3 | 900 | 400 | +500 | +500 |
Across these bars, total volume is 3,600 contracts: every ask and bid execution added together. Net delta is only +500. Volume describes activity; delta describes its classified imbalance. Neither number tells you the eventual direction of price without the price chart.
A CVD candle or line may display intrabar changes differently, but its closing running total still depends on the underlying classification. If an indicator estimates signed volume from price direction instead, the arithmetic can look similar while the input means something different.
Bar delta, CVD and footprint delta are different views
| View | Question it answers | Main limitation |
|---|---|---|
| Bar delta | Which side initiated more volume in this bar? | One bar hides the broader sequence. |
| Cumulative delta | How has net aggression developed since the reset? | Aggregation hides where trades happened. |
| Footprint delta | Where did classified buying and selling execute? | Detail still needs location and price context. |
Two sessions can end at the same cumulative value after completely different paths. One may trend steadily; another may alternate between large positive and negative bursts. A single closing number erases that sequence and all the prices at which it occurred.
When you need to investigate a failed breakout, look inside the move. The footprint chart guide explains the price-by-price view. CVD helps you spot a question worth asking; the footprint can help you examine it.
Cumulative delta divergence: compare effort with result
A divergence is a disagreement between comparable price swings and delta swings. A common bullish example is price making a lower low while CVD makes a higher low. Selling aggression may be weaker on the second push. A common bearish example is price making a higher high while CVD makes a lower high.
There is another pattern worth separating: CVD makes a new extreme while price does not. For instance, buying aggression reaches a new high but price cannot clear an earlier high. That can be consistent with passive selling absorbing the purchases. It is not the same observation as less buying aggression on a fresh price high.
Neither pattern proves a reversal. A trending market can keep diverging while price continues. Quote changes, thin liquidity, the chosen reset and a noisy swing definition can also affect what you see. “Divergence” is the beginning of a hypothesis, not permission to fade a move.
Compare swings within the same contract, session definition and reset. Avoid choosing a tiny price pivot and a completely different delta pivot just because the lines produce an attractive story. Record the comparison rule before using it in replay.
Absorption: strong delta without price progress
Imagine ES testing a prepared resistance area. Ask-executed volume keeps accumulating, but repeated pushes fail to hold above the area. Aggressive buying is present; upward progress is not. Passive sellers are a plausible explanation for the failed advance.
That is an absorption hypothesis, not proof that a particular institution is short. CVD alone cannot identify the trader, the hidden order size or the reason for the transaction. Read the actual price response and, if your tools permit, inspect executed volume at the relevant prices.
Iceberg orders are one possible source of replenishing liquidity. Absorption and icebergs are related but not interchangeable: multiple participants can also supply liquidity, and a resting order can eventually be exhausted.
The practical failure condition matters. If price starts holding above the area and building upward progress, do not keep calling every positive print trapped buying. New evidence can invalidate the original interpretation.
A practical ES and NQ decision sequence
My toolchain keeps analysis and execution separate: ExoCharts for orderflow, TradingView connected to Tradovate for execution, and Tradecopia when I copy my own trade across accounts. That does not make CVD a mandatory trigger for every trade or turn its settings into a universal strategy.
- Choose the location first. Mark the area you want to assess before price arrives. A divergence in the middle of an unplanned range is not automatically meaningful.
- Define the market context. Is this a range test, a breakout attempt or a pullback in an established trend? The same delta pattern can mean different things in each.
- Observe effort and result. Is aggressive volume producing progress, failing to move price, or weakening on the next test?
- Specify confirmation and invalidation. Decide what price behaviour would support the hypothesis and what would disprove it. Do not add those rules after entering.
- Calculate risk independently. A visually impressive divergence does not justify larger size, a wider unplanned stop or extra attempts after your daily limit.
The TradingView level-mapping tutorial covers the chart preparation side. The evaluation risk plan covers why account risk must remain separate from how persuasive a setup looks.
Check the data before trusting the CVD indicator
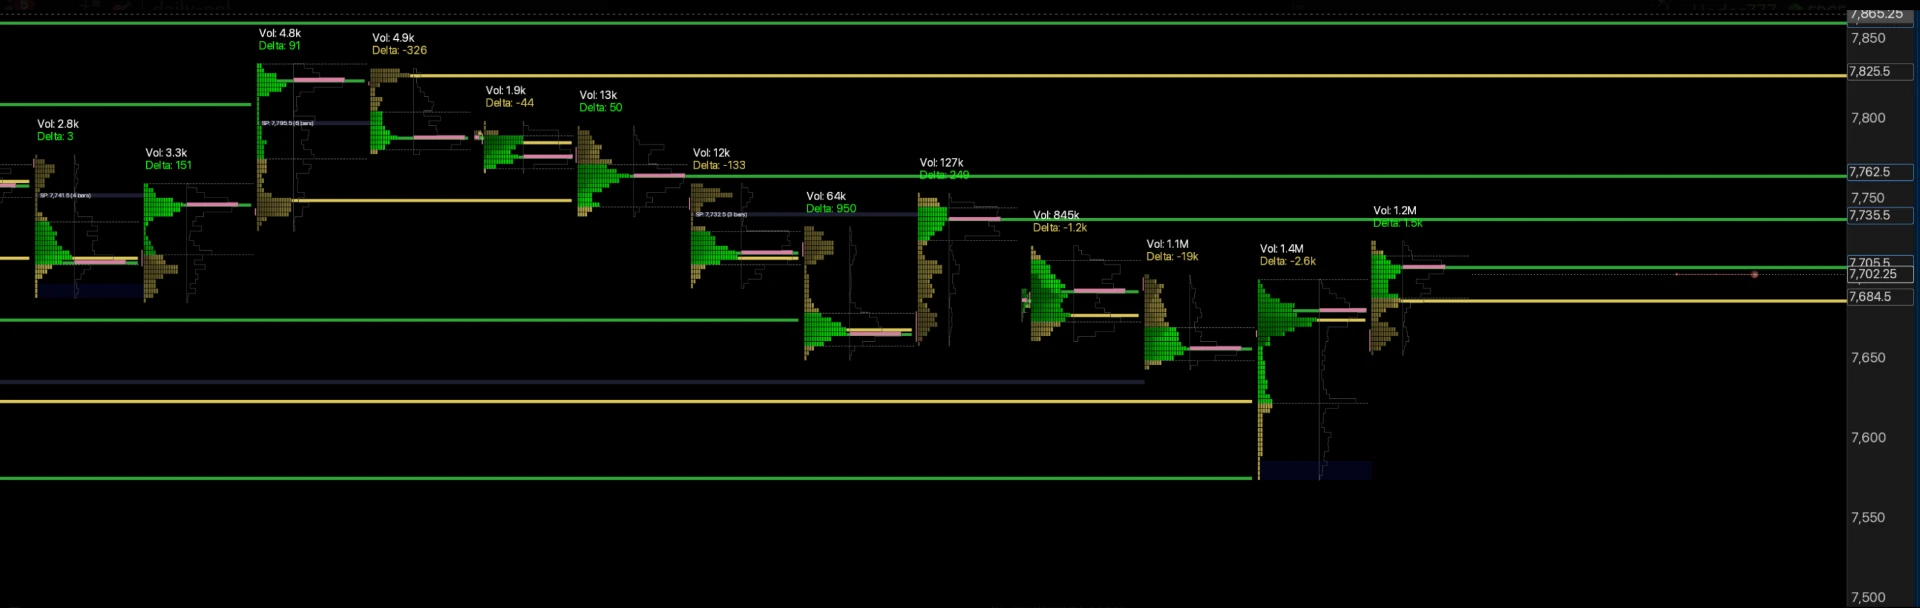
A chart labelled “CVD” is not enough to establish what it measures. Check whether it uses actual bid/ask trade classification, a tick rule, or lower-timeframe price-direction estimates. These methods can disagree without either chart being broken.
Historical coverage also matters. A live feed may contain information that an indicator cannot reconstruct identically from its available historical bars. Check your platform and feed documentation before assuming replay, historical and live values are directly comparable.
For TradingView specifically, read the selected indicator's current description instead of assuming every script measures exchange aggressor-side volume. An estimated volume-delta tool may still be useful, but its limitations need to be part of your interpretation. It should not be presented as identical to a bid/ask-based footprint.
Finally, confirm the instrument. A CFD proxy, a cash index, ES, MES, NQ and MNQ are not one shared order book. Related price movement does not imply identical delta. Analyse the traded contract's volume rather than comparing raw values from different instruments as though they were interchangeable.
Session resets, overnight trading and rollover
CVD's absolute value depends on where accumulation begins. An overnight-inclusive chart and a US cash-session reset can show different totals because they include different trades. Neither is inherently the correct one for every question.
Use a session definition that matches the setup you are studying and keep it consistent. A line crossing zero after a reset does not mean the market suddenly turned bullish. Zero is the calculation's reference point, not a universal support or resistance level.
Contract rollover adds another comparison problem. The volume migrates between contract months, and a continuous series may combine or adjust data. Record the contract and rollover treatment in your review. Avoid attributing a changed delta pattern to trader behaviour before checking whether the underlying series changed.
Want help interpreting delta at your levels?
In 1:1 mentorship we review your orderflow reads, invalidation and risk rather than treating every divergence as a trade. Mentorship also includes 12 months of Sato VIP. Limited spots.
Explore 1:1 MentorshipHow to practise without turning every divergence into a trade
Start with one clearly defined pattern at one type of location. In replay, record the level, the comparable price swings, the CVD reset, the data method and the price response. Save failed examples and ambiguous examples alongside the convincing ones.
Then ask whether the delta observation changed a decision you could have made from price alone. Did it help you skip a weak idea, wait for confirmation or recognise that aggression was making progress? If it only explained a chart after the move, it has not yet demonstrated practical value.
Do not infer a win rate from a handful of screenshots. Any strategy test needs defined entries, exits, fees and slippage, plus examples outside the period used to build it. A useful orderflow observation and a profitable trading system are different claims.
The takeaway: cumulative delta describes aggression, not certainty. Read it at a relevant location, compare it with price and let invalidation—not attachment to the indicator—govern your decision.
Last updated 2026-10-16. No specific CVD software settings, performance figures or trading results are promised. Platform calculations and available data vary.
Read Orderflow With a Map
Get my daily ES & NQ preparation as context. Your entries, confirmation, position size and risk remain your decisions; these are not trade signals.
Daily preparation and context — not trade signals.
Cumulative delta FAQ
What is cumulative delta in trading?+
Cumulative delta is a running total of signed traded volume from a chosen starting point. In a bid/ask implementation, volume executed at the ask counts positively and volume executed at the bid counts negatively. It measures classified trade aggression, not the number of buyers minus sellers.
How is cumulative volume delta calculated?+
For each bar, subtract bid-executed volume from ask-executed volume, then add that delta to the previous cumulative total. The result depends on the reset point, session definition and trade-classification method.
What is the difference between volume and delta?+
Volume measures all traded contracts. Delta subtracts one classified side of that volume from the other. A high-volume bar can have almost zero delta when aggressive buying and selling are similar.
Does positive delta mean more buyers than sellers?+
No. Every executed contract has a buyer and a seller. Positive bid/ask delta means more volume was classified as buyer-initiated, typically trading at the ask, than seller-initiated at the bid.
What is a bullish cumulative delta divergence?+
A common example is price making a lower low while CVD makes a higher low. That can suggest less aggressive selling on the second test, but does not confirm a reversal. Location, price response and invalidation are still necessary.
Can price fall while cumulative delta rises?+
Yes. Aggressive buyers can transact into resting sell liquidity without lifting price. Price can also move as quotes and liquidity change. Positive CVD is not a guarantee that price will rise.
Is TradingView cumulative delta the same as bid/ask delta?+
Not necessarily. An implementation may estimate buying and selling from lower-timeframe price movement instead of using exchange bid/ask trade classification. Read the indicator's current documentation and compare like-for-like data before interpreting the values.
Should cumulative delta reset every session?+
There is no universal reset. A session reset can help intraday comparisons; a longer accumulation answers a different question. Keep the same reset and session definition when comparing swings or testing a setup.
Does cumulative delta work on ES and NQ?+
It can describe executed aggression on either futures contract when the feed and implementation support it. ES and NQ values are not directly interchangeable, and neither chart provides a standalone entry signal or guaranteed edge.